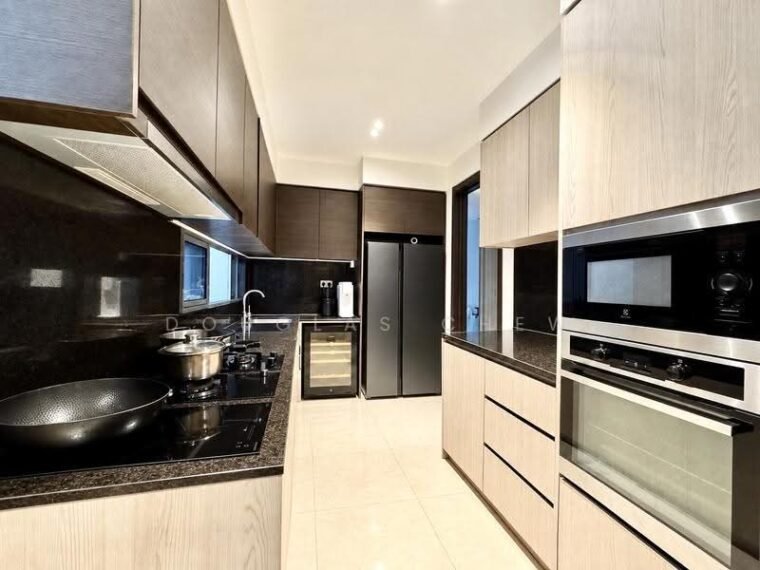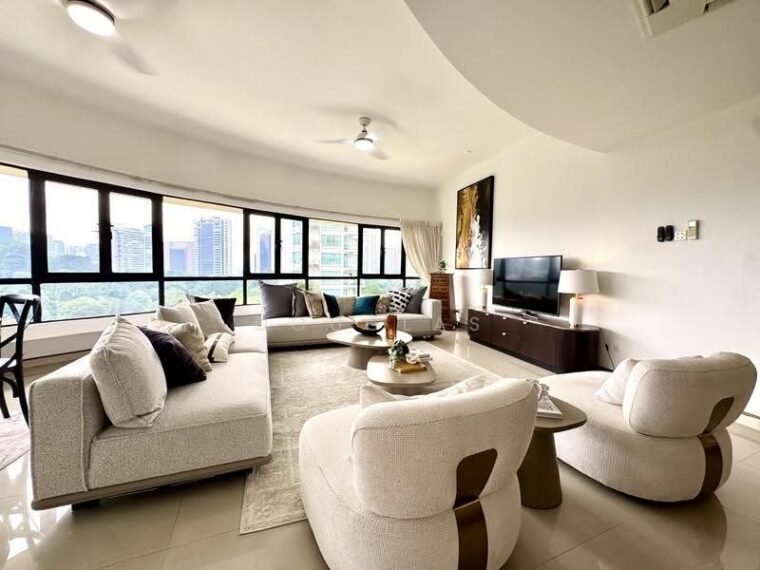
Showflats are very good at their job. The lighting, the furniture scaled slightly small, the route you walk, all of it is designed, and none of it tells you whether the unit is priced well.
The price list is the honest document
Ask for it before the tour, and look across the whole development rather than at the unit you have been shown.
Price per square foot by stack, by floor and by facing. The developer has thought about every one of those numbers, and the pattern tells you what they believe the market will pay for. A stack priced noticeably below its neighbours is not a bargain the developer missed. It is usually the afternoon sun, or a view into a car park, or the lift lobby on the other side of the bedroom wall.
The units that hold value in a launch are rarely the cheapest ones.
What the launch discount is actually worth
Early bird pricing, absorbed stamp duty, furniture vouchers: strip them out and compare net prices.
Developers price in tiers and release in phases. A genuine early phase advantage exists on some projects. On others, the later phases are priced at the same level and the urgency was manufactured. You find out by comparing the net figure against resale in the same area, not by being told.
Think about the exit before the entry
This is where the 2025 change bites hardest, and most buyers have not caught up with it.
Seller’s Stamp Duty now runs for four years on property bought on or after 4 July 2025, at 16% in year one, 12%, 8% and 4%. It used to be three years, and the rates were four percentage points lower at every step.
On a new launch, you buy years before you get keys. If anything changes for you in that window, a job, a posting, a family situation, the cost of unwinding is materially higher than it was in 2024.
That is not a reason to avoid new launches. It is a reason to be honest about how fixed your plans are.
What you can actually borrow
Progressive payments make the early years feel light. They do not change what you have to qualify for upfront.
On a first housing loan, up to 75% of price or valuation, with at least 5% in cash. Repayments across all your debts must fit inside 55% of gross monthly income, tested at 4% a year rather than at the promotional rate you were quoted.
That stress test is why people are sometimes approved for less than they expected on a launch that looked comfortable on the payment schedule.
New launch against resale
A new launch gives you a fresh 99 year lease, a warranty period, nothing to renovate and a staggered payment schedule.
Resale gives you the actual unit rather than a floor plan, the actual light at four in the afternoon, the actual noise, and usually a lower price per square foot.
Both are reasonable. The comparison just has to be run on the same basis, which takes about twenty minutes and almost nobody does it.
Bring the project you are looking at. Reading a price list for somebody is the easiest useful thing an agent does.
Figures checked October 2026. ABSD, BSD and SSD rates are set by IRAS, loan limits by MAS, CPF rules by the CPF Board, and flat rules by HDB. These change, sometimes overnight. Nothing here is tax or financial advice, and your own position depends on your profile, your timing and your lender. Check the current figure before you commit to anything.