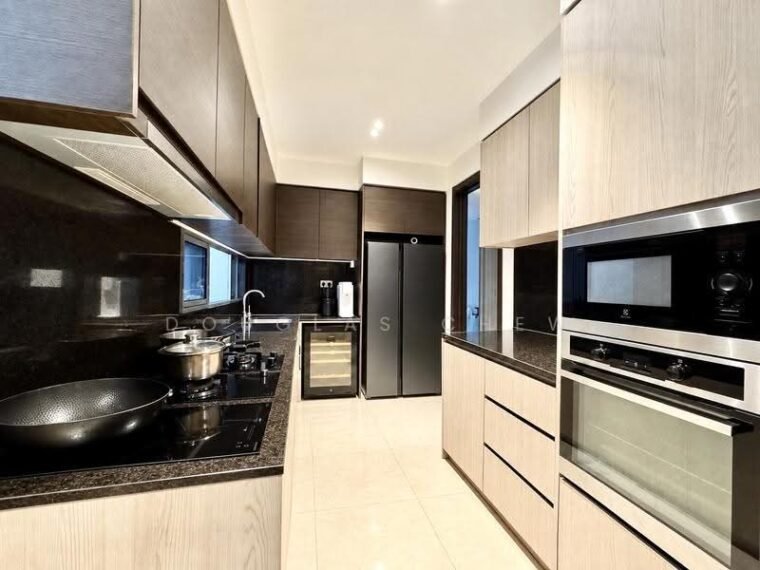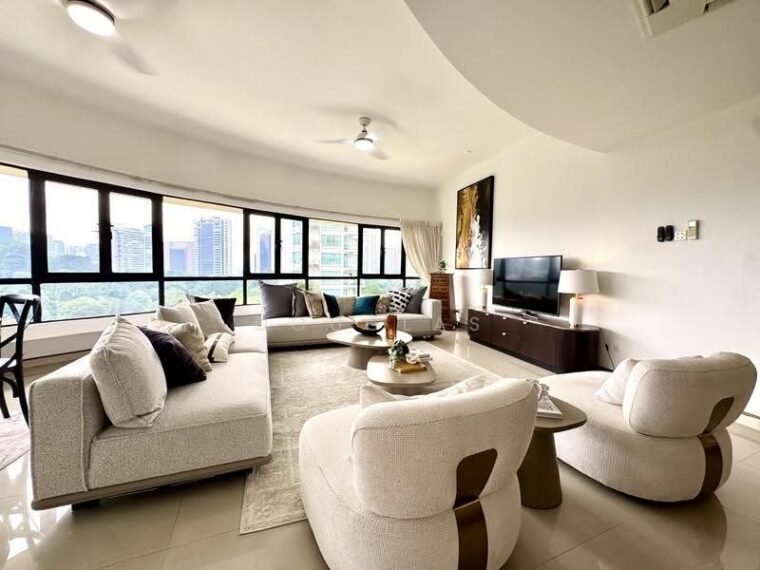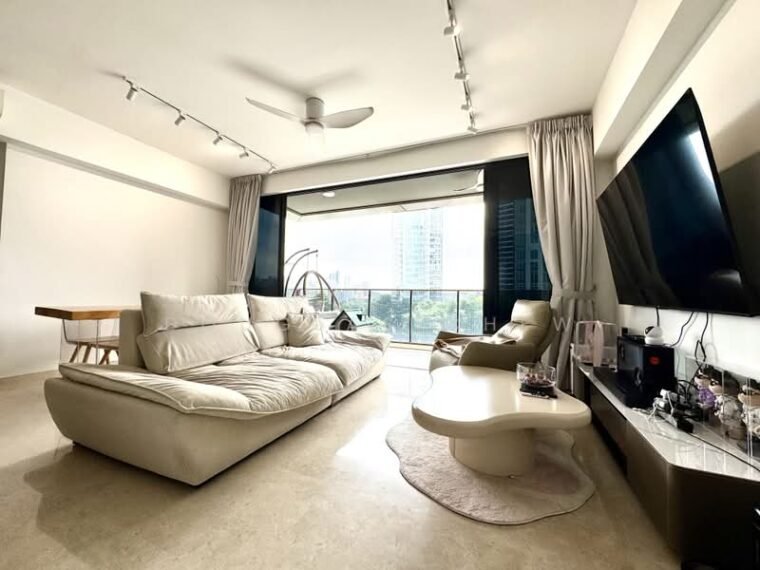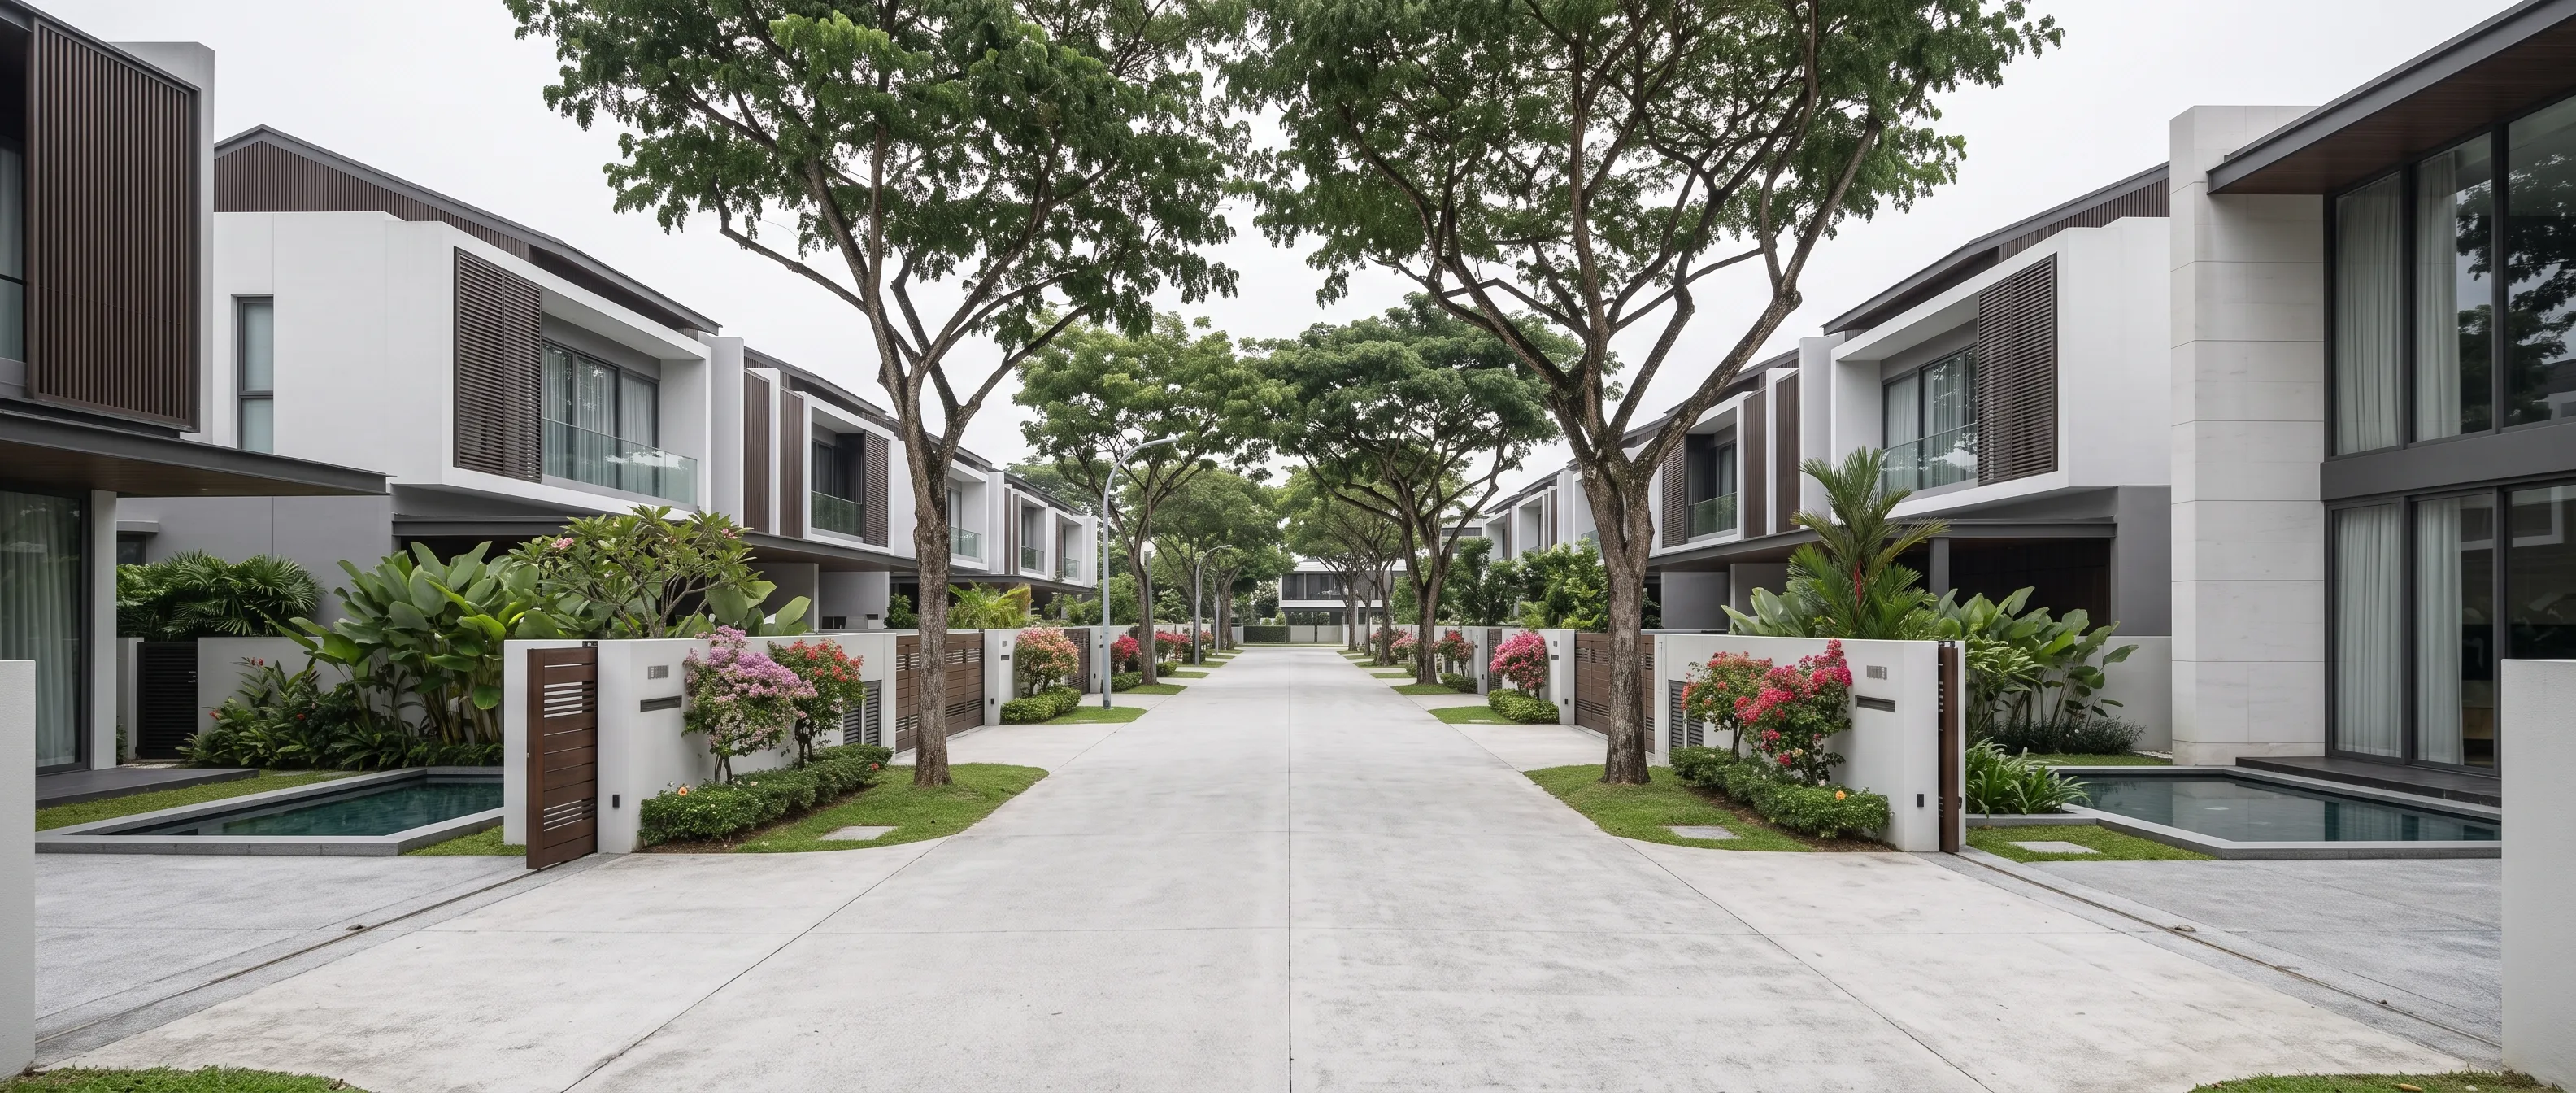
The project
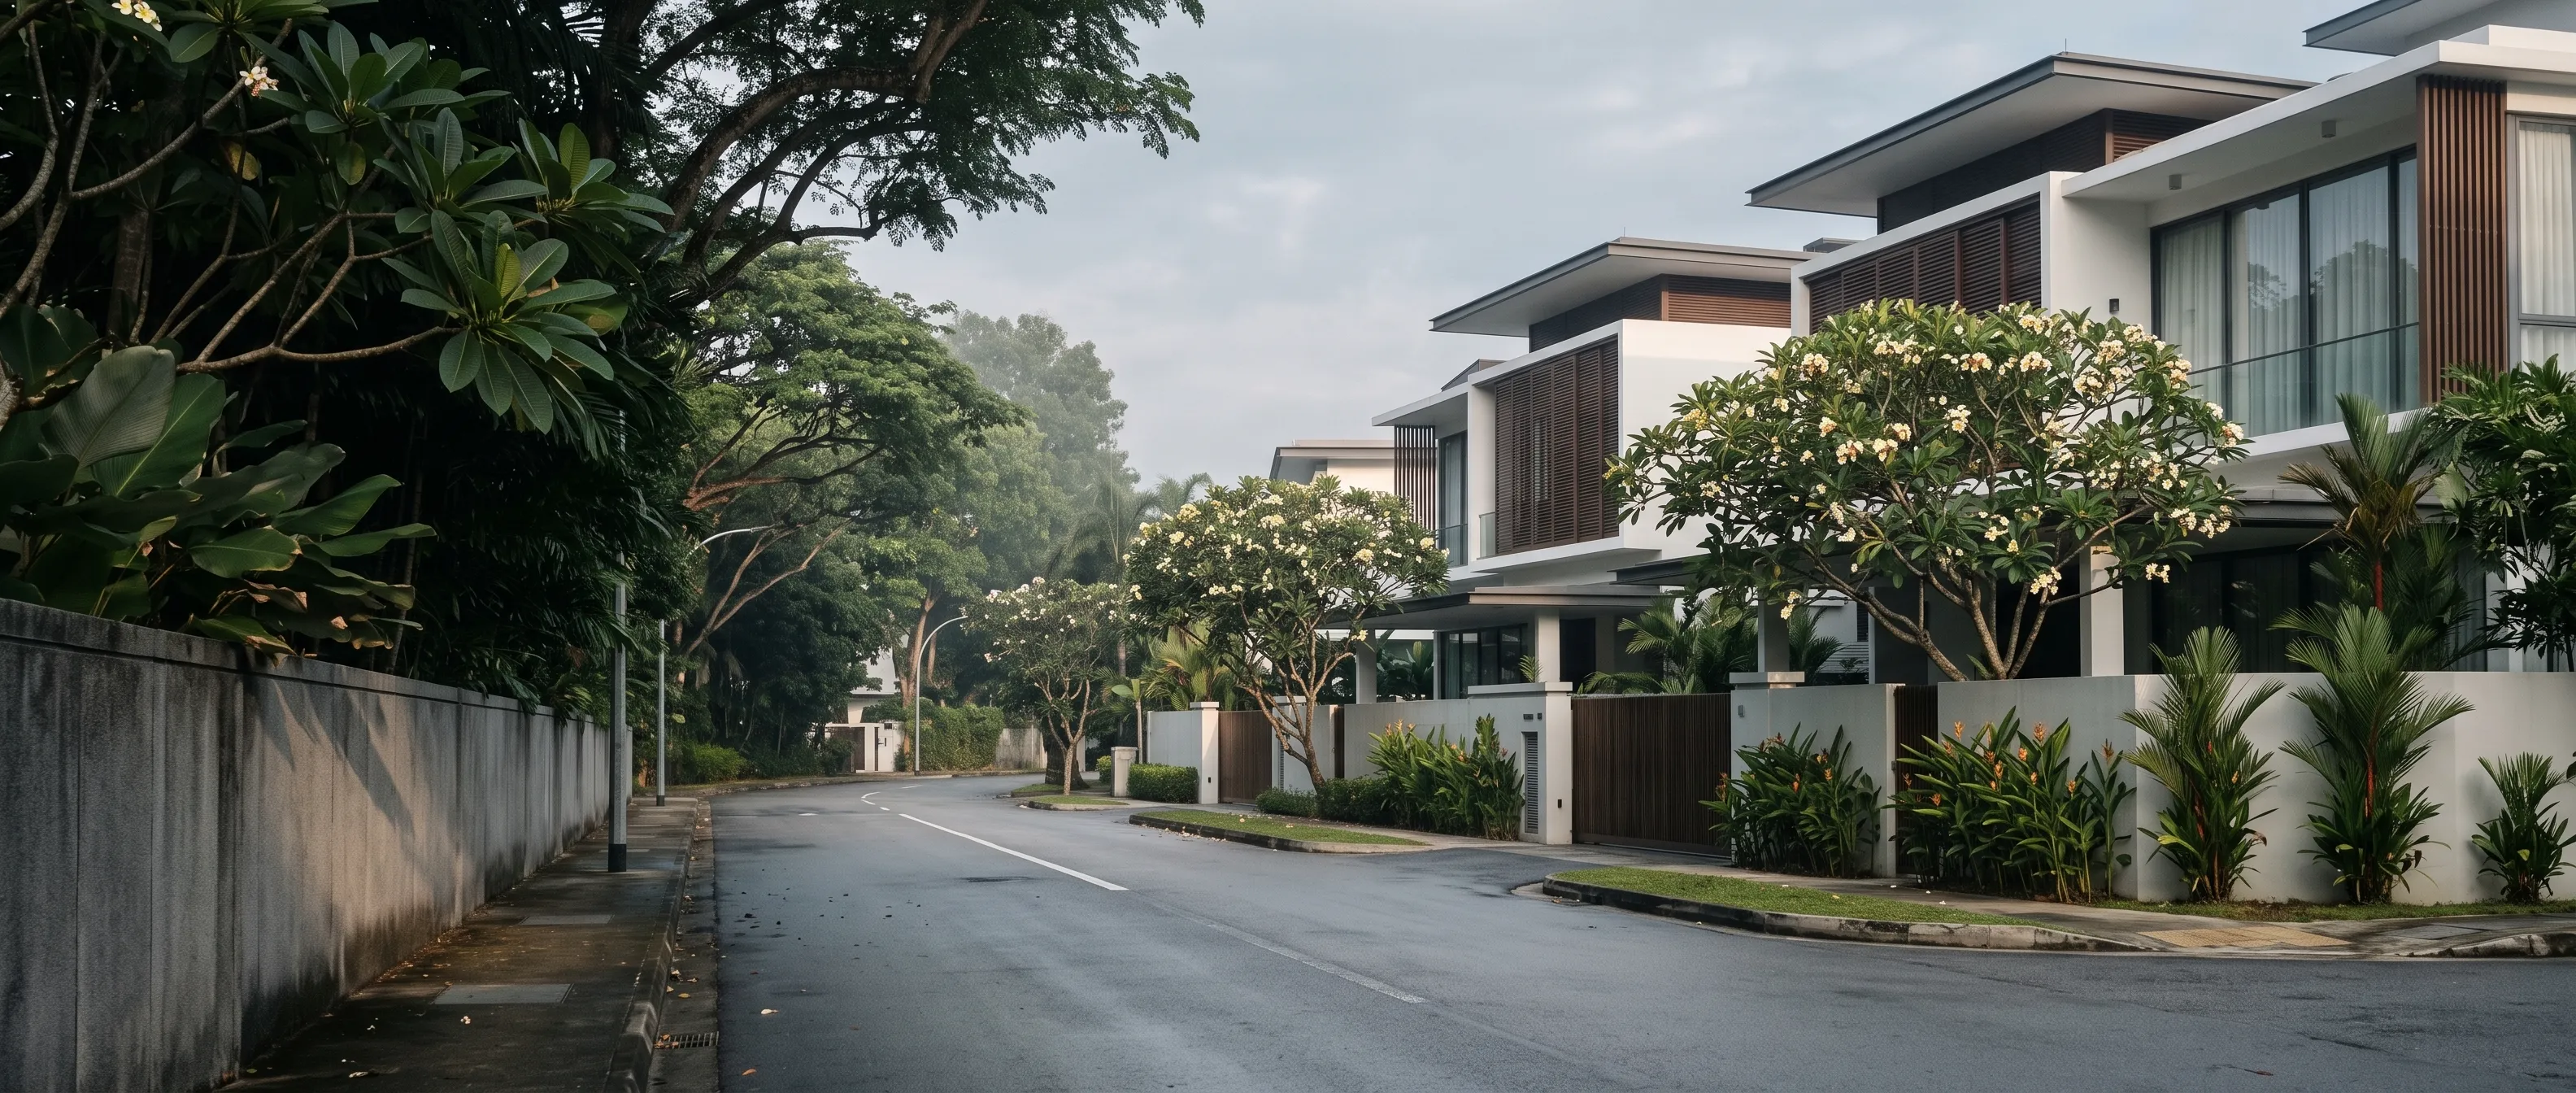
Parc Clematis sits on the former Park West site along Jalan Lempeng, 99 year leasehold, TOP 2023. It is a large development, which matters here: in a project of that size, the scarce layouts are the ones that hold their price.
The unit in this example is a five bedroom of 1,711 sqft, asking S$4,038,000, which works out at about S$2,360 per square foot. Five bedroom units at this size are the hardest to find once a project is substantially sold, and that scarcity is most of the argument for the price.
Clementi MRT and the town centre are a short drive, with one-north and the NUS belt close enough to matter for the people who typically buy here.
The move, step by step
The family were upgrading. What follows are the figures from their move.
| Previous home sold for | figure to be confirmed |
|---|---|
| Outstanding loan cleared | figure to be confirmed |
| CPF principal plus accrued interest refunded | figure to be confirmed |
| Cash actually in hand after the refund | figure to be confirmed |
| Purchase price paid here | figure to be confirmed |
| Sold first or bought first | to be confirmed |
| ABSD paid and reclaimed | to be confirmed |
| First valuation to keys | to be confirmed |
The gap between the second row and the fourth is the part people do not plan for. The sale price is not the budget. What is left after the loan and the CPF refund is the budget, and on a home held a long time the refund is a large number.
Why this layout
Five bedrooms across 1,711 sqft is the layout most growing families want and the one that is hardest to find once a project is fully sold. Buyers looking for that configuration in this area have few alternatives, which cuts both ways: it supports the price on the way in, and it supports it on the way out.
The smaller buyer pool is the trade-off. A large layout moves more slowly in a soft market. That is worth knowing going in rather than discovering later.
What made it work
Nothing clever. The valuation was done before anything was viewed, the MOP and ABSD position were confirmed in writing before an Option was signed, and the two completion dates were negotiated to meet rather than overlap.
Most of the cost in an upgrade is not in the price. It is in the month of two mortgages, the bridging that was not needed, or the deadline that forced a sale below value.
If you are weighing a similar move, the same sheet can be built for your own numbers in about half an hour.
Figures checked October 2026. ABSD, BSD and SSD rates are set by IRAS, loan limits by MAS, CPF rules by the CPF Board, and flat rules by HDB. These change, sometimes overnight. Nothing here is tax or financial advice, and your own position depends on your profile, your timing and your lender. Check the current figure before you commit to anything.